Yes, Zopa is generally considered a safe and legitimate UK digital bank.
It is authorised by the Prudential Regulation Authority (PRA), regulated by the Financial Conduct Authority (FCA) and PRA, and eligible deposits are protected by the Financial Services Compensation Scheme (FSCS) up to £120,000 per person, per authorised bank.
However, choosing a bank involves more than checking its regulatory status. Customers should also consider financial stability, fraud prevention, account restrictions, customer service, complaint handling and whether their particular financial product qualifies for statutory protection.
Zopa has grown from a peer-to-peer lending platform into an established digital banking business offering savings accounts, personal loans, credit cards, a current account and investment products.
Its financial results show continued profitability, while customer feedback highlights both the advantages of convenient mobile banking and the frustrations that some customers experience.
We analysed Zopa’s published financial performance, regulatory information, independent customer feedback and publicly available security arrangements to assess how trustworthy the bank is in 2026.
Our overall editorial safety rating is 87 out of 100, reflecting strong regulatory and deposit protections alongside some customer-service and operational considerations.
Is Zopa a Legitimate and Regulated Bank in the UK?
Zopa is a legitimate UK banking institution operating under the same fundamental regulatory framework as other authorised UK banks.
The business originally launched as a peer-to-peer lending platform in 2005 before securing its banking licence in 2020. It subsequently moved away from peer-to-peer investing to focus on consumer banking and lending.
Unlike an unregulated financial website or an electronic-money service operating without its own banking licence, Zopa Bank Limited is authorised to accept eligible customer deposits.
| Regulatory information | Zopa Bank details |
| Registered company | Zopa Bank Limited |
| Company number | 10627575 |
| FCA firm reference number | 800542 |
| Banking licence | UK-authorised bank |
| Regulatory authorities | FCA and PRA |
| FSCS deposit protection | Up to £120,000 |
| Banking launch | 2020 |
| Banking model | Digital-first |
| Physical branch network | No |
| Official website | zopa.com |
The PRA supervises the financial safety and soundness of banks, including their capital and liquidity requirements. The FCA oversees the conduct of authorised financial firms and relevant consumer protections.
Customers can independently verify the bank using the FCA Firm Checker.
Search for Zopa Bank Limited, and confirm that the firm reference number is 800542.
This check is particularly important because criminals sometimes create fraudulent websites that impersonate legitimate lenders.
A regulated banking licence provides meaningful consumer protection, although it does not guarantee that the bank can never experience technical failures, customer disputes or financial difficulties.
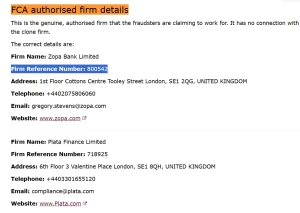
Zopa Bank Limited’s regulatory status and firm reference number 800542 on the official FCA Financial Services Register.
What Is Our Zopa Safety Rating for 2026?
Our overall editorial rating: 87% (4.35/5)
We assessed Zopa using five areas relevant to UK banking customers: regulatory authorisation, deposit protection, app security, published financial performance and customer outcomes.
| Assessment category | Editorial score | Weight |
| Banking regulation and authorisation | 92% | 25% |
| FSCS protection for eligible deposits | 95% | 25% |
| Digital security and fraud controls | 84% | 20% |
| Published financial stability indicators | 84% | 15% |
| Customer experience and complaint handling | 70% | 15% |
| Overall weighted rating | 87% | 100% |
The calculated weighted result is 86.65%, rounded to 87%.
These percentages represent our editorial assessment of the publicly available evidence. They are not independently audited security scores, customer survey results or estimates of the probability of Zopa failing.
Why Did We Give Zopa 87%?
Zopa scores strongly for its established banking authorisation, deposit-protection arrangements and reported profitability.
Its security controls are consistent with what customers would expect from a regulated digital bank, including identity verification, card-management tools and transaction monitoring.
However, a strong banking licence does not eliminate the possibility of account access problems, fraudulent payments or disputes over lending products.
Customer complaints, app dependence and the absence of physical branches are relevant limitations.
Our assessment is that Zopa offers substantial protection for ordinary banking and eligible savings, although customers should avoid treating any single financial provider as completely risk-free.
Is Your Money Safe in Zopa Under FSCS Protection?
One of the strongest reasons to trust Zopa with eligible savings is its participation in the Financial Services Compensation Scheme.
The FSCS is the UK’s statutory compensation scheme for customers of eligible financial firms that fail.
From 1 December 2025, the standard deposit-protection limit increased from £85,000 to £120,000 per eligible person, per authorised banking institution.
This higher limit applies to qualifying Zopa deposits in 2026.
Customers can verify the protection rules through the official FSCS website.
If Zopa Bank were to fail and could not repay eligible customer deposits, the FSCS would provide compensation subject to the scheme’s terms.
How Much Money Does FSCS Protect?
| Total eligible Zopa deposits | Standard protected amount | Amount above standard limit |
| £5,000 | £5,000 | £0 |
| £20,000 | £20,000 | £0 |
| £50,000 | £50,000 | £0 |
| £100,000 | £100,000 | £0 |
| £120,000 | £120,000 | £0 |
| £150,000 | £120,000 | £30,000 |
| £200,000 | £120,000 | £80,000 |
These examples assume one eligible depositor with no other deposits under the same banking authorisation and no special temporary-high-balance entitlement.
Suppose someone holds £80,000 in Zopa Smart Saver and another £60,000 in an eligible Zopa Cash ISA.
Their combined deposits would total £140,000.
Under the normal FSCS rules, £120,000 would be protected, leaving £20,000 outside the standard limit.
Opening multiple savings pots with the same bank does not create a separate £120,000 allowance for each pot.
Customers holding larger amounts may therefore benefit from spreading savings between banks operating under separate licences.
Those considering multiple tax-free savings products should also understand the rules surrounding Cash ISAs with different providers.
What About Temporary High Balances?
The FSCS provides additional protection for certain qualifying temporary high balances.
These may arise after significant life events, such as receiving an inheritance or selling a main residence.
Eligible temporary high balances can be protected up to £1.4 million for six months, subject to the scheme’s detailed conditions.
This additional protection is not available for every large deposit.
The source of the money, timing and eligibility requirements matter.
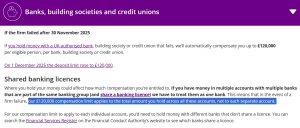
FSCS deposit protection increased to £120,000 per eligible person from 1 December 2025.
Is Zopa Financially Stable in 2026?
Financial stability is an important part of banking safety, especially for customers deciding where to hold substantial savings.
We reviewed Zopa’s published financial results rather than relying solely on banking awards or customer ratings.
Zopa reported its third consecutive profitable year in 2025, with underlying profit before tax of approximately £65 million.
The bank also expanded its customer base and lending activities.
Its financial performance continued to evolve during the first half of 2026.
Zopa Financial Performance
| Financial indicator | Reported result | Period |
| Underlying profit before tax | £65 million | Full year 2025 |
| Revenue | £377.1 million | Full year 2025 |
| Retail deposits | £6.4 billion | December 2025 |
| Customers | 1.7 million | December 2025 |
| Group revenue | £211.9 million | H1 2026 |
| Group statutory profit before tax | £18.1 million | H1 2026 |
| Retail deposits | Approximately £5.8 billion | June 2026 |
| Customers | 1.9 million | June 2026 |
| Liquidity coverage ratio | 419% | H1 2026 |
The full-year 2025 and half-year 2026 figures cover different reporting periods, while the profit measures also use different accounting definitions. They should not be interpreted as directly comparable annual profit results.
Customer numbers increased by approximately 26% year-on-year to June 2026, while group revenue rose by approximately 20% compared with the first half of 2025.
These figures indicate that Zopa continued growing its customer relationships and banking operations.
Nevertheless, its deposit balance declined from approximately £6.4 billion at the end of 2025 to £5.8 billion in June 2026.
Zopa explained that its excess liquidity allowed it to avoid actively attracting additional deposits at higher interest rates while managing funding costs.
This is a useful distinction. Falling deposits do not automatically indicate financial distress, but changes in deposits, liquidity and funding should still be monitored.
Does Zopa Have Enough Liquidity?
Liquidity refers to a bank’s ability to meet financial obligations, including withdrawals and payments, as they fall due.
Zopa reported a liquidity coverage ratio of 419% for the first half of 2026.
The regulatory minimum liquidity coverage ratio is generally 100%, meaning the bank’s reported figure was substantially above that benchmark.
A high liquidity coverage ratio is a positive indicator, but it does not guarantee that a bank is immune to all potential financial problems.
Customers should also consider capital adequacy, lending quality, profitability and operational risks.
Jaidev Janardana, Zopa Bank’s Chief Executive Officer, commented on the company’s 2025 performance:
“2025 was another landmark year for Zopa as we expanded into everyday banking.”
His statement accompanied Zopa’s announcement of its third consecutive profitable year.
Our interpretation is that Zopa’s reported profitability and customer growth support confidence in the business, although management statements should be considered alongside independently verifiable financial disclosures.
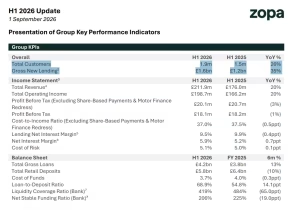
Zopa’s H1 2026 financial performance, including customer growth, revenue, deposits and liquidity.
Is the Zopa Banking App Secure From Hackers and Fraud?
Zopa operates primarily through its mobile banking application, making digital security central to its service.
The bank describes several protective arrangements, including identity verification, biometric access options, transaction monitoring and payment controls.
Zopa also states that it has achieved ISO 27001 certification and PCI DSS Service Provider Level 1 compliance.
These are recognised information-security and payment-card standards.
However, certification does not mean a company is completely protected from cyberattacks or operational incidents.
1. Biometric Authentication
Zopa supports security methods including fingerprint or facial recognition through compatible devices and relevant authentication processes.
Biometric access can reduce the risk of someone entering an account using a stolen password alone.
For certain banking processes, additional verification may also be required.
Customers should still protect their phones, device passcodes and account recovery information.
2. Card Freezing and Management
Zopa customers can freeze supported payment cards through the app.
For the Biscuit debit card, customers can access the Spend section and select the card-management controls to freeze or unfreeze the card.
This feature can help reduce the risk of further unauthorised card activity if a card is lost or stolen.
The availability of these controls is especially useful when comparing digital banks such as Monzo and Zopa.
3. Identity Verification
Zopa uses identity-verification checks when customers apply for relevant products.
These can involve checking identification documents and matching a selfie to the applicant’s identity.
Such checks reduce some types of identity fraud, although they cannot prevent every fraudulent application.
4. Transaction Monitoring
Zopa states that it monitors transactions to help identify suspicious financial activity.
Its security systems may interrupt or decline payments that appear unusual.
While this is intended to protect customers, legitimate transactions can sometimes be delayed or restricted for additional checks.
This creates an important trade-off between fraud prevention and immediate account access.
5. Protection Against Unsafe Devices
Zopa’s published app guidance explains that certain device conditions can interfere with access.
For example, the app may refuse to operate normally on rooted or jailbroken devices or when potentially unsafe software is detected.
This reflects security controls designed to reduce exposure to compromised devices.
Customers should download the official app through recognised app stores and keep their devices updated.
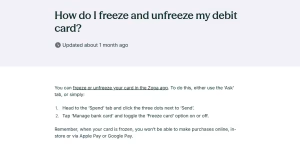
Zopa’s official guidance explaining how customers can freeze and unfreeze their debit cards.
Can You Get Scammed While Using Zopa?
Yes. Customers can still become victims of fraud even when using a regulated bank.
Banking scams commonly involve criminals impersonating financial providers, creating fraudulent loan websites or persuading victims to transfer money.
An especially important issue is the existence of fraudulent businesses using names similar to Zopa.
The FCA has published warnings about unauthorised firms impersonating legitimate financial companies, including names such as Zopa Personal Loans (UK).
These operations are not the genuine Zopa Bank Limited.
Customers should be particularly cautious if someone claiming to represent Zopa unexpectedly requests an advance fee to release a loan.
Other warning signs include:
- Requests to transfer money to a personal account before receiving a loan.
- Messages containing suspicious login links.
- Unsolicited offers promising guaranteed loan approval.
- Requests for passwords, verification codes or confidential security information.
- Pressure to move savings into a supposedly safer account.
The safest approach is to contact Zopa using details independently obtained from its official website or app.
Avoid relying on contact numbers supplied in suspicious messages.
Will Zopa Refund Scam Victims?
The answer depends on how the money was lost, the payment method and the circumstances.
Since 7 October 2024, mandatory reimbursement requirements have applied to eligible authorised push payment scams involving relevant UK payments.
Under these rules, eligible customers may receive reimbursement of up to £85,000 per claim.
A bank may apply an excess of up to £100 in certain cases, while additional protections apply to qualifying vulnerable customers.
Claims are generally expected to be resolved within five business days, although some investigations can take longer.
These protections are separate from FSCS deposit protection and do not mean that every fraudulent or disputed payment must automatically be refunded.
Customers should report suspected fraud immediately and provide any relevant evidence.
For everyday account management, understanding how to cancel a Direct Debit can also help customers respond quickly to unwanted recurring payments.
Is Zopa Safe for Savings Accounts and Cash ISAs?
Zopa’s savings products are among its most important offerings.
Its range includes Smart Saver, Fixed Term Savings and Cash ISA products.
These accounts can suit different savings objectives, but they do not all offer identical withdrawal arrangements.
| Zopa product | Main purpose | Important safety consideration |
| Smart Saver | Flexible cash savings | Eligible deposits qualify for FSCS protection |
| Access savings pots | Savings with accessible funds | Interest rates may vary |
| Notice savings pots | Savings requiring advance withdrawal notice | Access restrictions apply |
| Fixed Term Savings | Locking in an interest rate | Money generally cannot be withdrawn before maturity |
| Cash ISA | Tax-efficient cash savings | FSCS protection applies to eligible deposits |
| Stocks and Shares ISA | Long-term investing | Market losses are not covered by deposit protection |
Is Zopa Smart Saver Safe?
Smart Saver is a regulated savings product offered through Zopa Bank.
Eligible deposits are protected under the standard FSCS rules.
However, customers should understand the difference between easy-access, notice and fixed-term arrangements.
An account may be secure from a deposit-protection perspective while still having withdrawal restrictions.
Are Zopa Fixed Term Savings Safe?
Fixed-term savings provide a predetermined interest rate for a specified period.
The main consideration is access.
Once money has been deposited into a fixed-term pot, customers generally cannot withdraw it until the agreed term ends.
Therefore, money intended for unexpected expenses may be better held in an accessible savings account.
Is Zopa Cash ISA Safe?
Eligible cash deposits held in a Zopa Cash ISA receive applicable FSCS deposit protection.
However, customers should understand ISA subscription rules and any charges or interest penalties associated with early withdrawals from particular fixed-term ISA products.
When comparing Zopa’s ISA offerings with Nationwide ISA rates or Yorkshire Building Society ISA rates, it is important to assess withdrawal flexibility as well as the advertised interest rate.
A higher rate does not necessarily make an account more suitable if access is restricted.
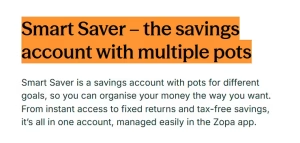
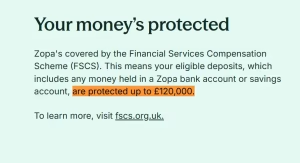
Zopa’s official Smart Saver and fixed-term savings information showing product features and FSCS protection.
Are Zopa Investments as Safe as Zopa Savings?
No. Investments and cash savings carry different risks.
Zopa offers investment products that are fundamentally different from ordinary bank deposits.
For eligible investment claims, FSCS protection can apply up to £85,000 per person, per firm, subject to the relevant rules.
However, this protection does not compensate investors simply because the value of their investments falls.
For example, suppose someone invests £10,000 and the market value declines to £8,500.
The £1,500 investment loss is not reimbursed merely because the product has a relationship with an FSCS-protected provider.
This distinction is important for customers transitioning from traditional savings to investments.
Unlike cash savings held within statutory protection limits, investment returns are not guaranteed.
Customers comparing investment platforms should also understand how withdrawals, investment ownership and cash arrangements work. Our explanation of withdrawing money from Trading 212 covers another important aspect of accessing investment funds.
Is Zopa Safe for Personal Loans and Credit Cards?
Zopa is a regulated consumer lender offering personal loans and credit cards.
However, safety in borrowing should be assessed differently from safety in saving.
When taking out a loan, the main financial risk is not losing a protected bank deposit. It is borrowing more than can reasonably be repaid or accepting expensive lending terms.
Customers should assess:
- The annual percentage rate (APR).
- Total repayment amount.
- Monthly affordability.
- Length of the repayment agreement.
- Late-payment consequences.
- Potential effects on credit history.
A regulated lender must comply with applicable consumer-credit requirements, but regulation does not guarantee that every loan offer will be inexpensive or suitable.
For someone already managing outstanding debts, comparing loan options for bad credit can help clarify eligibility, affordability and potential borrowing costs.
Zopa credit-card customers may also benefit from statutory consumer protections, including Section 75 of the Consumer Credit Act where the relevant conditions are met.
Section 75 can make a credit-card provider jointly liable with a supplier for certain qualifying purchases costing more than £100 and no more than £30,000.
This is a separate form of consumer protection from FSCS coverage.
Customers should also consider the consequences of withdrawing cash from a credit card, as cash withdrawals can attract different fees and interest arrangements.
Our assessment is that Zopa is a credible regulated borrowing provider, but customers should compare the individual terms rather than assuming that a trustworthy bank automatically offers the best borrowing deal.
What Do Real Customers Say About Zopa in 2026?
Customer reviews provide useful information about everyday banking experiences, although they should not be confused with independent financial or cybersecurity audits.
In our review of publicly available feedback, Zopa held a Trustpilot rating of approximately 4.6 out of 5, supported by more than 38,000 reviews at the time checked.
Trustpilot’s displayed breakdown included approximately 88% five-star reviews and 6% one-star reviews.
These percentages describe the reviews on that platform, not the proportion of all Zopa customers who are satisfied or dissatisfied.
Zopa also performed positively in independent savings-provider research.
In Which?’s published savings analysis, Zopa received a customer score of 74% and an interest-rate assessment score of 80%, compared with an overall provider average of 76% for interest rates in that research.
These results suggest that Zopa has competitive strengths in savings rates and its digital experience.
What Customers Like About Zopa?
Positive reviews frequently highlight straightforward applications, convenient account management and an accessible mobile app.
Customers also mention competitive savings products and the ability to manage financial accounts without visiting a branch.
These advantages are consistent with Zopa’s digital-first banking model.
What Complaints Do Customers Raise?
Negative reviews include experiences involving account restrictions, payment disputes, problems contacting support and disagreement over charges or loan-related issues.
These reports should be considered carefully.
A negative review does not necessarily establish that the bank acted incorrectly, while a positive review cannot verify the security of its underlying infrastructure.
It is also important to distinguish experiences involving savings accounts from those involving credit cards, loans or vehicle finance.
A customer’s complaint about lending charges should not automatically be interpreted as evidence that eligible bank deposits are unsafe.
How Many Complaints Has Zopa Received?
An assessment of Zopa’s safety should consider official complaints information rather than relying exclusively on review-platform ratings.
The FCA’s firm-level complaints data for the first half of 2026 provides additional insight.
| Zopa complaints indicator | H1 2026 |
| Banking and credit-card complaints opened | 6,118 |
| Complaints per 1,000 banking and credit-card accounts | 3.78 |
| Banking and credit-card complaints closed within three days | 49.94% |
| Banking and credit-card complaints upheld | 46.33% |
| Credit-related complaints opened | 14,186 |
The credit-related category is reported separately and should not be confused with banking and credit-card complaints.
The FCA’s data also shows that the banking and credit-card complaint rate was lower than the 4.51 complaints per 1,000 accounts reported for the preceding half-year period.
This represents an improvement in that particular metric.
Nevertheless, a substantial volume of complaints remains relevant when assessing customer outcomes.
Complaint figures require context because different financial businesses have different customer bases, products and reporting classifications.
Our assessment is that Zopa’s reported figures do not suggest that the bank is illegitimate, but they reinforce the importance of customer support and transparent dispute resolution.
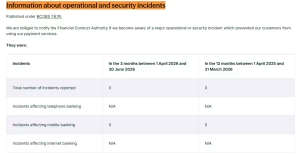
FCA complaints data for Zopa Bank Limited, covering January to June 2026.
What Are the Disadvantages of Banking With Zopa?
Although Zopa offers considerable advantages, several limitations deserve attention.
No Traditional Branch Network
Zopa is designed primarily for digital banking.
Customers who prefer visiting a branch to discuss financial concerns may find this inconvenient.
This is especially relevant for individuals who are uncomfortable managing important financial transactions exclusively through a mobile application.
Dependence on Technology
App-based banking depends on access to a functioning device, an internet connection and the provider’s systems.
A temporary technical issue can therefore become frustrating if a customer urgently needs to access money.
Zopa’s own published service information reported zero major operational or security incidents requiring regulatory notification during April to June 2026, and zero in the preceding 12-month reporting period.
This is a positive disclosed operational indicator, but it does not mean that no individual customer ever experienced a login, payment or service problem.
Account Restrictions and Verification
Banks are required to take financial crime prevention seriously.
This sometimes involves identity checks, unusual-transaction reviews or restrictions on account access.
Although these controls are intended to protect customers, they can cause difficulties when access to money is urgent.
For this reason, keeping access to an alternative bank account is a sensible precaution.
Savings Access Restrictions
Not all Zopa savings products provide immediate access to money.
Notice and fixed-term products may restrict withdrawals or impose conditions on early access.
Customers should carefully read the account terms before depositing funds needed for emergencies.
Interest Rates Can Change
Variable-rate savings products can become less competitive over time.
A high initial savings rate should not be treated as a guarantee of future returns.
Comparing alternative providers periodically can help customers avoid leaving money in an account that no longer meets their financial objectives.
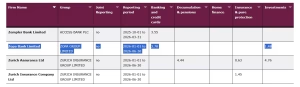
Zopa’s published operational and security incident disclosure for its personal current account.
Is Zopa Safer Than Other Digital Banks?
Zopa operates within the same broad UK banking regulatory framework as other authorised banks, including Monzo and Starling.
However, comparing banking providers requires more than checking whether they offer FSCS protection.
Different banks have different product ranges, support arrangements, security features and customer experiences.
| Comparison factor | Zopa | What customers should consider |
| UK banking authorisation | Yes | Verify the legal banking entity |
| Standard FSCS deposit limit | £120,000 | Protection applies per eligible person and banking licence |
| Mobile banking | Yes | App reliability and security |
| Physical branch network | No | Access to in-person support |
| Savings products | Yes | Interest rates and access conditions |
| Consumer lending | Yes | APR and repayment affordability |
| Investment products | Yes | Market risk and separate protection rules |
| Customer support | Digital and telephone channels | Availability and complaint resolution |
Customers who are primarily interested in mobile account security may also wish to examine whether Starling Bank is safe.
Those comparing everyday digital accounts can consider the different features offered by Revolut and Monzo.
The most suitable bank depends on whether someone prioritises savings rates, everyday payments, borrowing, customer support or access to physical branches.
No single provider is necessarily the best choice for every financial requirement.
What Happens if Zopa Bank Goes Bust?
If Zopa were to fail, eligible depositors would be covered by the FSCS compensation process, subject to the relevant limits.
The FSCS normally aims to compensate eligible customers of failed banks within seven working days, although more complex cases can take longer.
For example, someone holding £60,000 in qualifying Zopa savings would normally fall fully within the standard deposit-protection limit.
Someone holding £160,000 would have £40,000 above the standard individual limit, unless additional protections applied.
This is why understanding banking licences and deposit aggregation is more important than simply dividing savings between different pots.
Customers with larger balances should consider distributing money across genuinely separate authorised institutions.
Having an alternative accessible account can also help manage temporary disruption while any compensation or account-recovery process takes place.
How Can You Keep Your Zopa Account Safe?
Banking security is a shared responsibility between the institution and its customers.
Even sophisticated fraud-prevention systems cannot stop every scam.
We recommend taking the following precautions:
- Use the official app: Download it through the recognised Apple or Google app stores.
- Verify unexpected communications: Contact Zopa independently instead of responding to suspicious messages.
- Keep devices updated: Install relevant operating-system and banking-app security updates.
- Protect login information: Never share passwords, authentication codes or recovery details.
- Monitor transactions: Investigate unfamiliar payments as soon as possible.
- Freeze lost or stolen cards: Use the relevant card-management controls.
- Understand account conditions: Check withdrawal rules before choosing a savings product.
- Stay within FSCS limits where practical: Consider separate banking licences for substantial cash balances.
- Maintain an alternative account: This can provide access to funds during technical problems or account reviews.
- Report suspected fraud immediately: Contact the bank and preserve relevant transaction evidence.
For customers holding significant cash savings, a compound interest calculator can also help estimate how interest may affect the balance held with a bank over time.
Should You Trust Zopa With Your Money in 2026?
Zopa has several characteristics associated with a credible UK banking institution.
It operates under UK banking regulation, participates in statutory deposit protection and publishes financial performance information.
Its reported profitability, substantial customer base and liquidity indicators strengthen the case for considering it a legitimate banking provider.
Nevertheless, customers should evaluate the actual product they intend to use.
For a saver holding an eligible balance below £120,000, Zopa’s deposit-protection arrangements provide an important financial safeguard.
For someone investing through Zopa, the risks are different because investment values can fall.
For borrowers, affordability and lending terms are more important than deposit protection.
Our overall assessment is that Zopa is a credible choice for many UK customers, particularly those comfortable with app-based banking.
However, customers holding substantial funds, requiring branch access or depending on uninterrupted banking services should consider whether a second banking relationship would improve their financial resilience.
Conclusion: Is Zopa Safe?
Zopa is a legitimate and regulated UK bank offering meaningful financial protections to customers. Its eligible deposits are protected up to £120,000 by the FSCS, and its published financial results show an established, profitable banking business.
Our overall editorial safety rating of 87% reflects strong regulatory protection, digital security arrangements and financial performance, balanced against customer complaints and practical limitations associated with app-based banking.
For everyday savings and banking, Zopa is a credible option. However, customers should understand product-specific risks, check withdrawal conditions and avoid keeping amounts above the standard deposit-protection limit without considering alternative arrangements.
Frequently Asked Questions About Zopa Safety
Is Zopa a real bank?
Yes. Zopa Bank Limited is a legitimate UK-authorised bank regulated by the FCA and PRA. Its FCA firm reference number is 800542.
Is Zopa protected by FSCS?
Yes. Eligible deposits are protected up to £120,000 per person, per authorised banking institution under the standard FSCS deposit-protection rules applying from December 2025.
Can Zopa Bank go bust?
Like any commercial bank, Zopa is not completely immune to financial failure. However, its regulatory supervision and statutory deposit protection provide important safeguards for eligible customers.
Is Zopa safe for large savings?
Eligible deposits are protected up to the standard FSCS limit. Customers holding more than £120,000 should consider spreading money across separately authorised banks.
Is the Zopa app secure?
Zopa uses identity verification, authentication controls, card management and transaction monitoring. However, customers should still protect their devices and remain alert to phishing and impersonation scams.
Does Zopa have physical bank branches?
No. Zopa is a digital-first bank without a traditional high-street branch network. Customers primarily manage their accounts through its app and available support channels.
Is Zopa Smart Saver safe?
Yes, eligible Smart Saver deposits benefit from FSCS protection. Customers should still check the interest rate, account terms and withdrawal arrangements.
Are Zopa investments guaranteed?
No. Investment values can rise or fall. FSCS investment protection does not reimburse ordinary market losses.
Is Zopa safe for personal loans?
Zopa is a regulated UK lender. However, borrowing suitability depends on the APR, repayment terms, affordability and the customer’s financial circumstances.
What should I do if Zopa freezes my account?
Contact Zopa through its official support channels and follow any identity-verification instructions. If the issue remains unresolved, make a formal complaint and consider the Financial Ombudsman Service where appropriate.
Is Zopa safer than Monzo?
Both are legitimate UK-regulated banks offering statutory protection for eligible deposits. The better choice depends on account features, customer service, savings products and individual requirements.
Can Zopa customers lose money to scammers?
Yes. Fraudsters can target customers of any bank. Eligible victims of certain authorised push payment scams may qualify for reimbursement under UK rules, but not all losses are automatically covered.