The State Pension triple lock forecast for 2027 has become a confirmed 3.9% increase, bringing the full new State Pension to £250.70 per week, or £13,036.40 annually, from April 2027.
The increase follows the latest earnings and inflation figures released during September and October 2026. Average earnings growth of 3.9% was higher than September inflation of 3.5% and the triple-lock minimum of 2.5%.
For people receiving the full new State Pension, this means an additional £488.80 a year, while those entitled to the full basic State Pension will receive an extra £374.40 annually.
However, the October 2026 Budget introduced another important development. The full new State Pension will exceed the standard £12,570 Personal Allowance for the first time, prompting the government to introduce a Pension Tax Allowance from April 2027.
Our analysis of the latest pension announcements shows that the financial consequences extend beyond a straightforward 3.9% payment increase. Income Tax, Pension Credit, National Insurance records and future triple-lock reforms will all influence retirement planning.
What Is the Latest State Pension Triple Lock Forecast for 2027?
The State Pension triple lock increase for April 2027 has been confirmed at 3.9%, following the government’s October 2026 Budget announcement.
The DWP subsequently published its proposed pension payment rates for the 2027/28 financial year on 11 November 2026.
The confirmed percentage and published payment rates provide a substantially clearer position than earlier forecasts, which suggested that the increase might fall between 3.4% and 4.1%.
Latest Triple-Lock Figures
| Triple-lock measure | Relevant 2026 figure | Outcome |
| Average earnings growth, May–July 2026 | 3.9% | Highest measure |
| CPI inflation, September 2026 | 3.5% | Below earnings |
| Minimum triple-lock guarantee | 2.5% | Below earnings |
| 2027 State Pension increase | 3.9% | Confirmed uprating |
The decision means earnings growth, rather than inflation, determines the increase for the second consecutive year.
The pension will increase from 6 April 2027, with the first payment reflecting the uprating depending on each recipient’s payment schedule.
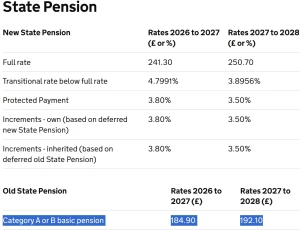
Official DWP State Pension rates for 2027/28, showing the full new State Pension increasing from £241.30 to £250.70 per week.
How Much Will the State Pension Increase in April 2027?
The 3.9% increase will raise the annual value of the full new State Pension above £13,000 for the first time.
Our calculations using the published weekly rates show the following changes.
| Payment period | 2026/27 | 2027/28 | Increase |
| Weekly | £241.30 | £250.70 | £9.40 |
| Every four weeks | £965.20 | £1,002.80 | £37.60 |
| Monthly equivalent | £1,045.63 | £1,086.37 | £40.74 |
| Annually, 52 weeks | £12,547.60 | £13,036.40 | £488.80 |
The figures are based on the full rate rather than the amount received by every pensioner.
State Pension is usually paid every four weeks, meaning recipients should not mistake the monthly equivalent for their normal payment amount.
An individual receiving £200 per week in 2026/27, for example, should not assume that they will automatically receive £250.70 in 2027/28.
Their entitlement depends on their contribution history and applicable pension rules.
For a personalised estimate, our UK State Pension calculator helps illustrate how qualifying years and retirement circumstances may influence payments.
However, the calculator currently uses 2026/27 reference figures, so the official State Pension forecast should remain the primary source for individual entitlement.
How Much Extra Income Does the Increase Provide?
For someone entitled to the full new State Pension throughout the year:
- Extra weekly income: £9.40
- Extra four-week payment: £37.60
- Additional annual income: £488.80
- Percentage increase: 3.9%
From a household budgeting perspective, the additional annual income is meaningful, particularly where retirement spending is concentrated on food, energy, transport and essential services.
Nevertheless, pensioners should assess the increase alongside household inflation rather than treat every additional pound as an improvement in purchasing power.
What Will the Basic State Pension Be in 2027?
People who reached State Pension age before 6 April 2016 are generally covered by the older State Pension system.
The full basic State Pension will also increase by approximately 3.9% from April 2027.
| Payment period | 2026/27 | 2027/28 |
| Weekly | £184.90 | £192.10 |
| Every four weeks | £739.60 | £768.40 |
| Monthly equivalent | £801.23 | £832.43 |
| Annually | £9,614.80 | £9,989.20 |
| Annual increase | — | £374.40 |
The new rate represents an additional £7.20 per week.
Importantly, some people receiving the old State Pension also receive Additional State Pension through SERPS or the State Second Pension.
These additional elements do not necessarily increase by the same 3.9% as the basic pension.
For 2027/28, Additional State Pension is scheduled to increase by 3.5%, reflecting the relevant inflation measure.
Consequently, someone receiving £192.10 in basic State Pension and another amount in Additional State Pension may have a different overall percentage increase from someone receiving only the full basic pension.
How Does the State Pension Triple Lock Work?
The State Pension triple lock is a government policy designed to protect the value of the basic and new State Pensions.
It increases the relevant pension rates annually by whichever of three measures is highest:
- Average earnings growth: The annual increase in average weekly earnings, including bonuses, measured over the May-to-July period.
- CPI inflation: The annual Consumer Prices Index inflation rate recorded in September.
- Minimum guarantee: A fixed 2.5% annual increase.
The government compares these measures before determining the following April’s uprating.
For April 2027, the calculation was:
3.9% earnings growth vs 3.5% inflation vs 2.5% guarantee = 3.9% increase.
This mechanism protects pensioners against inflation while also allowing the State Pension to rise alongside average wages when wage growth is stronger.
However, it does not guarantee that the State Pension will cover every individual’s retirement spending requirements.
A retiree experiencing higher-than-average energy, housing or care costs might face greater household inflation than the national CPI measure.
Our assessment is that the triple lock provides an important baseline of retirement income protection, but it should not be treated as a complete retirement financial plan.
How Does the 2027 Increase Compare With Previous Years?
The State Pension has experienced several unusually large annual increases because of inflation and earnings growth.
The comparison below highlights how the latest adjustment fits into recent pension policy.
| April increase | Triple-lock increase | Full new State Pension per week |
| 2023 | 10.1% | £203.85 |
| 2024 | 8.5% | £221.20 |
| 2025 | 4.1% | £230.25 |
| 2026 | 4.8% | £241.30 |
| 2027 | 3.9% | £250.70 |
The full new State Pension will therefore have increased from £203.85 per week in April 2023 to £250.70 in April 2027.
That represents an increase of approximately 23% over the four annual upratings.
While this is significant in cash terms, the period also included substantial increases in household living costs.
We therefore distinguish between nominal pension increases, which show changes in the amount paid, and real-terms changes, which account for the cost of goods and services.
Will the 3.9% State Pension Increase Beat Inflation?
The 2027 State Pension increase is 0.4 percentage points above September 2026 CPI inflation.
This is because:
- Earnings growth was 3.9%.
- September CPI inflation was 3.5%.
- The difference was 0.4 percentage points.
That comparison suggests a modest advantage over the inflation measure used in the triple-lock calculation.
However, September 2026 inflation does not establish how much prices will rise throughout the 2027/28 pension year.
The Office for Budget Responsibility’s October 2026 outlook projected that inflationary pressures would continue into 2027.
If household expenses rise more quickly than anticipated, some pensioners could find that the extra £488.80 in annual income provides limited additional spending flexibility.
For example, an increase in annual household expenses of £600 would exceed the additional £488.80 received by someone on the full new State Pension.
Their nominal pension would increase, but they could still experience pressure on their disposable income.
We consider this distinction important when evaluating whether the triple lock genuinely improves retirement living standards.
Will Pensioners Pay Income Tax on the State Pension in 2027?
The full new State Pension will exceed the standard Personal Allowance in 2027/28.
However, the government has introduced a new Pension Tax Allowance to prevent qualifying lower-income pensioners from facing an Income Tax liability solely because the State Pension has risen above the standard allowance.
The relevant figures are:
| Tax measure | 2027/28 amount |
| Standard Personal Allowance | £12,570 |
| Full new State Pension annually | £13,036.40 |
| Amount above Personal Allowance | £466.40 |
| Potential basic-rate tax without protection | £93.28 |
| Maximum tax reduction under Pension Tax Allowance | Approximately £94 |
Without the new arrangement, an individual whose only taxable income was the full new State Pension could face approximately £93.28 in annual Income Tax at the basic rate.
The Pension Tax Allowance is designed to eliminate that liability for qualifying pensioners.
How the Pension Tax Allowance Will Operate?
The allowance begins in the 2027/28 tax year and applies to people above State Pension age, including those reaching that age during the tax year, subject to the relevant income conditions.
It applies according to total income, not simply the amount of State Pension received.
| Total annual income in 2027/28 | Pension Tax Allowance position |
| Below £12,570 | Normally no Income Tax liability under the standard allowance |
| £12,570–£13,037 | Full Pension Tax Allowance available |
| £13,037–£13,319 | Allowance gradually reduced |
| £13,319 or more | No Pension Tax Allowance |
The allowance is gradually withdrawn by £1 for every £3 of income above the full annual new State Pension threshold.
HMRC will generally apply it automatically using the information available about a person’s income and State Pension age.
The government’s estimate is that approximately 290,000 pensioners will avoid paying tax because of the allowance in 2027/28, while around 500,000 will benefit from a tax reduction overall.
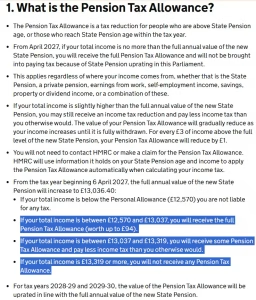
HM Treasury’s Pension Tax Allowance guidance explaining how pensioners with income around £13,036.40 will receive Income Tax protection from April 2027.
What Happens if You Receive a Private Pension Alongside the State Pension?
Retirees with workplace pensions, personal pensions, investment income or part-time employment must evaluate their combined taxable income.
The new Pension Tax Allowance does not provide unrestricted tax-free treatment for every pensioner.
Consider three illustrative situations.
| Retirement income situation | Total annual income | General tax position |
| Full new State Pension only | £13,036.40 | Qualifies for full Pension Tax Allowance |
| Full new State Pension plus £200 private pension income | £13,236.40 | Partial Pension Tax Allowance may apply |
| Full new State Pension plus £5,000 private pension income | £18,036.40 | Above Pension Tax Allowance withdrawal limit |
These illustrations assume the relevant income is taxable and that the individual qualifies for the standard Personal Allowance. Other reliefs and personal circumstances may change the calculation.
For people with several retirement income sources, the essential question is not simply whether the State Pension increases by 3.9%.
It is how the increase affects overall taxable income and the amount of money retained after tax.
The rules surrounding inherited pensions from 2027 also deserve attention where retirement or estate planning involves unused pension savings.
Importantly, the State Pension triple lock does not automatically determine increases in private pensions.
A defined benefit pension might increase according to scheme-specific inflation rules, while a defined contribution pension depends on investments, contributions and withdrawals.
What Is the State Pension Triple Lock Forecast for 2028?
Although the April 2027 increase is confirmed at 3.9%, the increase for April 2028 remains a forecast.
The Office for Budget Responsibility’s October 2026 economic outlook includes a 3.4% triple-lock assumption for 2028/29.
This is an economic projection rather than a guaranteed uprating.
If the 2028 increase were 3.4%, the full new State Pension could reach approximately £259.20 per week, subject to official rounding.
Illustrative Future Payment Projections
| Financial year | Increase | Full new State Pension weekly |
| 2026/27 | 4.8% | £241.30 |
| 2027/28 | 3.9% confirmed | £250.70 |
| 2028/29 | 3.4% OBR assumption | Around £259.20 |
| 2029/30 | Not yet determined | Not confirmed |
The 2028 figure may change as earnings growth and inflation data become available.
The final April 2028 increase will depend on the relevant May–July 2027 earnings figures, September 2027 inflation and the 2.5% minimum.
We would not recommend treating any long-term projection as guaranteed income when making binding retirement spending decisions.
An individual planning to retire in 2028 should therefore use a range of outcomes rather than assume that the latest projection will necessarily materialise.
Is the State Pension Triple Lock Ending in 2030?
The State Pension triple lock is not being abolished in April 2030, but the government has announced a significant adjustment to its calculation.
The existing arrangement will continue until April 2030.
Under the announced reform, future increases will be based on the highest of:
- CPI inflation.
- A minimum increase of 2.5%.
- The increase needed to maintain or restore the State Pension’s value relative to average earnings, measured against its 2029/30 level.
This is different from the current rule, which automatically awards the full annual earnings growth percentage whenever earnings are the highest measure.
Current Triple Lock Versus Adjusted Triple Lock
| Feature | Until April 2030 | From April 2030 |
| Minimum annual increase | 2.5% | 2.5% |
| Inflation protection | Yes | Yes |
| Earnings protection | Full annual earnings measure when highest | Maintains pension value relative to earnings over time |
| Long-term spending effect | Can permanently compound above earnings | Designed to reduce the long-term compounding effect |
| Policy status | Existing system | Announced reform |
The Office for Budget Responsibility has highlighted that the current triple lock creates a cumulative spending effect.
For example, when inflation exceeds average earnings, the resulting increase in State Pension value relative to wages is retained under the present system.
Future pension increases then build on that higher level.
The adjusted system is designed to maintain long-term earnings-related value without automatically preserving every temporary increase above earnings.
Jonathan Cribb, Deputy Director at the Institute for Fiscal Studies, explained the uncertainty behind the existing mechanism:
“The more volatile inflation and average earnings growth are, the higher the cost.”
His September 2026 analysis examined how changes in the relationship between inflation and earnings affect the long-term cost of the triple lock.
Our assessment is that the 2030 reform is an important distinction for workers in their 40s, 50s and early 60s, whose retirement projections may extend well beyond the current Parliament.
It does not reduce the announced 3.9% increase for April 2027.
Will Everyone Receive the Full £250.70 State Pension in 2027?
No. The full £250.70 rate applies to people entitled to the full new State Pension.
Individual payments may be lower or, in particular circumstances, higher.
The amount depends on several factors:
- The number of qualifying National Insurance years.
- National Insurance credits received.
- Contracting-out history before April 2016.
- Transitional State Pension calculations.
- Protected payments.
- Any applicable pension deferral.
People whose National Insurance record began after 5 April 2016 generally need 35 qualifying years for the full new State Pension and at least 10 years to qualify for any payment.
However, the position can be more complicated for people with contribution records beginning before April 2016.
For example, someone with 35 qualifying years may not automatically receive the full rate if earlier contracting-out or transitional arrangements affect their entitlement.
Equally, a person who spent years caring for children or family members may have acquired National Insurance credits without making conventional employment contributions.
Our detailed analysis of State Pension entitlement without paying National Insurance explains these differences and the circumstances in which voluntary contributions can improve retirement income.
What About Pensioners With Protected Payments?
A protected payment can arise where a person’s entitlement under the transitional new State Pension calculation exceeded the full rate when the new system was introduced.
Protected payments are not necessarily increased by the triple-lock percentage.
For 2027/28, the protected payment element is scheduled to increase by 3.5%, while the relevant full new State Pension rate increases by 3.9%.
This explains why two retirees receiving similar weekly pensions may see different percentage increases in their total payments.
Will Pension Credit Increase Alongside the State Pension in 2027?
Pension Credit is an income-related benefit designed to support eligible pensioners with lower incomes.
It is separate from the State Pension, and the triple lock does not automatically determine every Pension Credit rate.
The DWP’s proposed 2027/28 rates show the following changes in the standard minimum guarantee.
| Pension Credit standard minimum guarantee | 2026/27 | 2027/28 |
| Single person | £238.00 | £247.30 |
| Couple | £363.25 | £377.40 |
These are weekly guarantee levels used within the Pension Credit calculation, not fixed payments awarded to every claimant.
Actual entitlement depends on assessable income, savings and other qualifying circumstances.
A pensioner whose State Pension increases may receive a corresponding adjustment to Pension Credit.
This means some lower-income households may experience a smaller increase in total household income than the headline State Pension uplift suggests.
The distinction matters particularly where Pension Credit is already topping up retirement income to the applicable guarantee level.
Pensioners should also consider other available assistance, including the £200 pensioner Winter Fuel Payment eligibility rules, where age, residence, household circumstances and income can influence the amount retained.
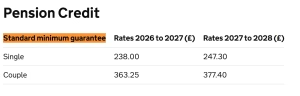
Proposed Pension Credit standard minimum guarantee rates for single pensioners and couples in 2027/28.
How Will the 2027 State Pension Increase Affect Self-Employed People and Business Owners?
The new triple-lock figures are relevant not only to existing pensioners but also to directors, entrepreneurs and self-employed workers approaching retirement.
Unlike many employees, business owners often have greater control over how income is structured.
However, business income arrangements can affect National Insurance records and ultimately State Pension entitlement.
National Insurance and Director Remuneration
Company directors who primarily receive dividends should understand that dividend income does not ordinarily create National Insurance qualifying years.
A director receiving a modest salary may build State Pension entitlement if the applicable National Insurance conditions are satisfied.
Someone taking only dividends without otherwise accumulating contributions or credits may create gaps in their State Pension record.
For sole traders, the rules are different.
Eligible self-employed people may receive Class 2 National Insurance contributions treated as paid, depending on their profit level and the relevant tax-year rules.
This can protect State Pension entitlement without requiring an actual Class 2 payment in certain circumstances.
Our financial assessment suggests that business owners should review their National Insurance records alongside salary, dividend and retirement-planning decisions.
A tax-efficient arrangement in the present year is not necessarily the most appropriate arrangement when long-term pension entitlement is considered.
Workplace Pensions and Retirement Income
The State Pension should be viewed as one component of retirement income.
For workers with occupational pension schemes, including NHS employees, the retirement calculation may also involve defined benefit accrual and scheme-specific retirement ages.
Someone considering public-sector retirement can explore our NHS Pension calculator alongside the NHS pension entitlement after 20 years, where the relevant scheme rules affect final income.
The broader financial principle is that State Pension, workplace pension and personal savings should be considered together rather than in isolation.
Does the State Pension Age Change in 2027?
Yes. The UK State Pension age is increasing from 66 to 67 between 2026 and 2028.
The transition means that people born in different months can become entitled to the State Pension at different ages.
Someone approaching their 66th birthday in 2027 should not automatically assume they will qualify to claim immediately.
Their precise eligibility date depends on their date of birth.
Importantly, the State Pension age increase and the triple-lock uprating are separate policies.
The 3.9% uprating determines changes in the relevant weekly payment rates.
The State Pension age rules determine when someone becomes eligible to claim.
Therefore, a person who reaches State Pension age after April 2027 may receive the 2027/28 rate when their entitlement begins, but they do not receive payments for periods before they become eligible merely because the rate has increased.
What Should Pensioners Do Before April 2027?
Our analysis identifies five practical actions for pensioners and people approaching retirement.
- Check the latest State Pension forecast: Confirm the expected entitlement through the government’s forecast service, especially where National Insurance records extend before April 2016.
- Review qualifying National Insurance years: Missing contributions or credits can affect long-term entitlement. Voluntary contributions should only be considered after confirming they would increase the eventual pension.
- Assess total taxable retirement income: Include the State Pension, occupational pensions, earnings and other taxable income when estimating the impact of the new Pension Tax Allowance.
- Check Pension Credit and wider benefits: Low-income pensioners should review their entitlement, particularly where their circumstances have recently changed.
- Update retirement budgets: Use the confirmed 2027 rates, but avoid treating uncertain 2028 forecasts as guaranteed cash flow.
We also recommend checking that the DWP has the correct bank account and personal details before scheduled payments.
The State Pension is generally not paid automatically when a person reaches State Pension age. An eligible person usually needs to claim it.
Is the 2027 State Pension Increase Good News for Retirees?
The confirmed 3.9% increase provides a measurable improvement in nominal retirement income.
For someone receiving the full new State Pension, the additional £488.80 annually is approximately equivalent to £40.73 per calendar month when the annual increase is divided by twelve.
However, whether the change improves a pensioner’s financial position depends on inflation, taxable income and other retirement benefits.
Our Financial Assessment
| Area assessed | 2027 outcome | Our assessment |
| State Pension increase | 3.9% | Positive nominal income increase |
| Comparison with September CPI | 0.4 percentage points higher | Modest inflation benchmark advantage |
| Full new State Pension | £13,036.40 annually | Above £13,000 for first time |
| Income Tax exposure | Pension Tax Allowance introduced | Targeted protection for eligible pensioners |
| Pension Credit | Revised guarantee levels | Supports eligible lower-income households |
| 2028 pension forecast | 3.4% OBR assumption | Uncertain until later data |
| 2030 reform | Adjusted triple lock | Long-term planning implications |
We view the 2027 increase as financially beneficial, particularly because the government has introduced specific tax protection for pensioners with income around the full new State Pension level.
Nevertheless, we would not evaluate the policy solely through its headline percentage.
For retirees with substantial private pensions, the overall tax position may matter more.
For pensioners with modest incomes, interactions with means-tested benefits may be equally important.
And for younger workers, the adjusted triple lock from 2030 creates a different long-term forecasting environment.
Conclusion
The State Pension triple lock forecast for 2027 has been replaced by a confirmed 3.9% increase, taking the full new State Pension to £250.70 per week and the full basic pension to £192.10.
The increase provides valuable additional income, but the broader financial picture includes the new Pension Tax Allowance, updated Pension Credit rates and changes to the triple-lock system from April 2030.
Our analysis suggests that retirement planning should focus on individual entitlement, total taxable income and future spending requirements rather than the annual percentage increase alone.
While the 2028 outlook suggests further growth, those figures remain projections rather than guaranteed payment amounts.
Frequently Asked Questions
How much will the State Pension increase in April 2027?
The State Pension will increase by 3.9% from April 2027. The full new State Pension will rise to £250.70 per week, while the full basic State Pension will increase to £192.10.
What will the full State Pension be annually in 2027/28?
The full new State Pension will be worth £13,036.40 over 52 weeks. The full basic State Pension will be worth £9,989.20 annually.
Is the State Pension triple lock confirmed for 2027?
Yes. The government has confirmed the 3.9% uprating under the existing triple-lock system. The DWP has also published the proposed weekly rates for 2027/28.
Will pensioners pay tax on the full State Pension in 2027?
The annual full new State Pension will exceed the £12,570 Personal Allowance. However, the new Pension Tax Allowance will protect eligible pensioners whose total income is no more than the full annual new State Pension rate.
What is the predicted State Pension increase for 2028?
The OBR’s October 2026 forecast assumes a 3.4% increase for 2028/29. This is not confirmed and may change with future earnings and inflation figures.
Is the triple lock ending in 2030?
No. The government plans to adjust the triple lock from April 2030. Pension increases will continue to receive inflation protection and a 2.5% minimum, with a revised mechanism for maintaining value relative to earnings.
Will everyone receive £250.70 per week in 2027?
No. The amount depends on individual National Insurance contributions, credits and other pension rules. £250.70 is the full new State Pension rate, not a universal payment.